
Inflation hasn’t gone away — it’s going up. With the midterm elections seven weeks off, that’s an issue for the president and Congress. Voters hate inflation. They don’t very similar to the remedy both, and the remedy has two components. The Federal Reserve raising interest rates, like it just did, is one. The second half is neglected and within the palms of Congress. Certainly, the Fed can’t convey inflation down for good until lawmakers present they’ll again the debt with future fiscal surpluses. Which means changing into critical about overspending.
The Consumer Price Index exhibits costs rose 0.4% over the past month, and three.4% over the past 12 months. The Fed’s most well-liked measure of inflation, the Private Consumption Expenditures Value Index, isn’t especially reassuring, both.
Oil and gasoline costs, which have climbed as a consequence of circumstances in Iran and elsewhere, account for a considerable share of that enhance. However People nonetheless perceive the large image: Almost six years after our era’s “Nice Inflation” started, total costs proceed to rise a lot quicker than they need to, and nicely above the Fed’s 2% annual goal.
A brand new National Bureau of Economic Research paper exhibits why the priority stays so private. The authors checked out payroll information for about 16 million American staff between 2021 and 2024. As shock inflation was plaguing the financial system, peaking at 9% in 2022, companies had been handing out their customary 3% cost-of-living raises. In the meantime, 43% of staff who didn’t change jobs (and 37% of all staff studied) endured reductions in actual wages, most of which had been fairly extreme. Mixture actual wages have since recovered, however the floor misplaced within the interim was by no means regained.
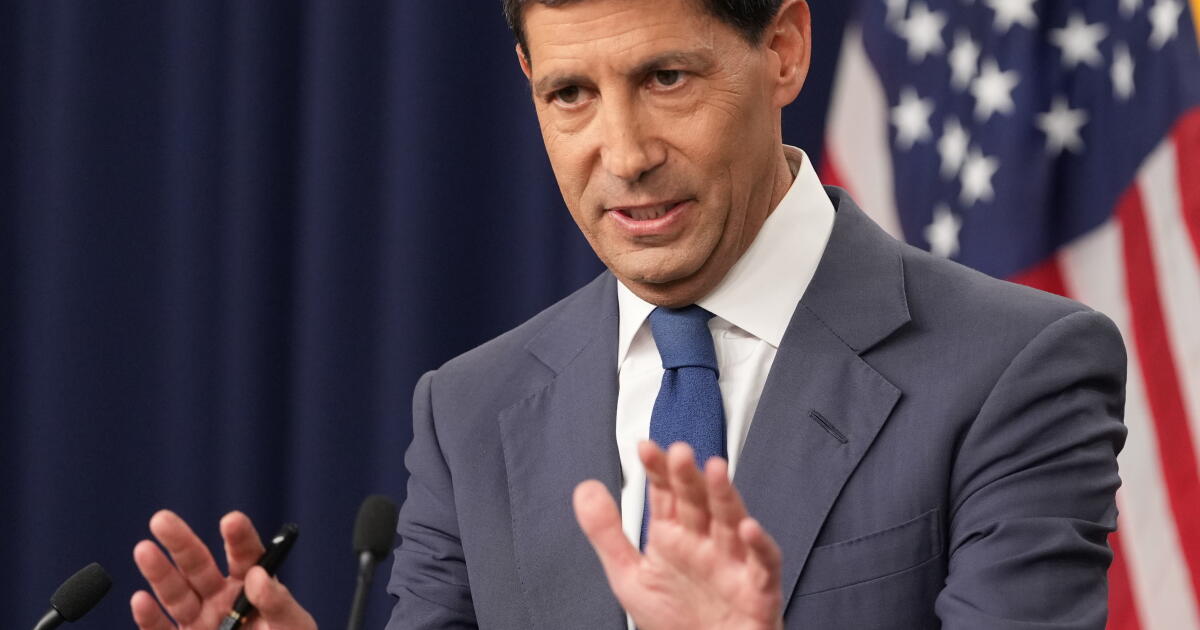
Contemplating that everybody claims to be a populist lately, you’d assume the Trump administration and Congress can be making inflation a clearer precedence. And by that, I definitely don’t imply pressuring Kevin Warsh, the brand new Fed chairman, to decrease rates of interest.
As an alternative, these officers act like beating inflation is solely the Fed’s job. It’s not.
In a world with out fiscal austerity, when the Fed will increase rates of interest to sluggish inflation, the nation’s curiosity funds on the debt develop, too. Which means extra authorities borrowing and extra claims on future tax income that no person expects to be absolutely collected. It’s a vicious cycle through which unaccounted-for cash can add gas to the inflation hearth.
To win his Nineteen Eighties struggle in opposition to inflation, the Fed’s then-chairman Paul Volcker was vocal with Congress and the Reagan administration about the truth that he couldn’t do it on his personal. What made Volcker’s disinflation stick was not only a willingness to lift charges. And it wasn’t that Washington ran smaller deficits, both — deficits practically tripled within the early Nineteen Eighties.
What mattered was that markets got here to consider a correction was coming. Congress handed the Tax Fairness and Fiscal Duty Act (TEFRA) in 1982, Social Safety reform in 1983, tax reform in 1986 and ultimately enabled the surpluses of the late Nineteen Nineties. Sadly, that lesson has been forgotten.
That brings us again to right this moment. Warsh has signaled some key shifts in Fed coverage, together with sustaining the two% inflation goal. In step with this dedication, he simply raised rates of interest by 0.25%, mountain climbing the ultimate determine to between 3.75% and 4%. Now, this Congress and subsequent ones should do their half. Parker Sheppard, senior fellow on the Fiscal Lab on Capitol Hill, spells out two ideas.
First, Congress ought to decide to a reputable deficit goal and restore the expectation that it’ll hold future debt sustainable. As Sheppard notes, “deficits are operating at 6% right this moment, and three% is a stage Congress has hit repeatedly.” True, trimming deficits by half shall be a critical political problem. However contemplating the political problem that inflation represents, it’s price doing.
Second, Sheppard argues that the Congressional Finances Workplace ought to embrace debt-service prices when it scores laws. As issues now stand, a invoice can spend cash in yr two and offset it in yr 9, and the rating comes out balanced. Legislators then vote on proposals priced as if this prices us nothing. However these seven years of borrowing usually are not free. The Treasury pays curiosity on each greenback within the interim, and at present charges, it’s vital cash that the rating by no means exhibits.
Financial progress helps, too. Eradicating laws that stand in the way in which of funding and work is efficacious by itself deserves, but it surely additionally helps with fiscal funds. The ensuing income expands the federal government’s capability to service its obligations on the margin and lessens inflationary strain.
All of that is price doing, although it received’t save us from the necessity to reform entitlement spending. Some 70% of the federal funds consists of necessary spending, and your entire projected enhance within the deficit comes from Social Safety and Medicare. Entitlement reform is what we must be aiming for.
So sure, we must always observe intently what the Fed does to struggle inflation. However we must always not let Congress off the hook.
Veronique de Rugy is a senior analysis fellow on the Mercatus Heart at George Mason College. This text was produced in collaboration with Creators Syndicate.
